

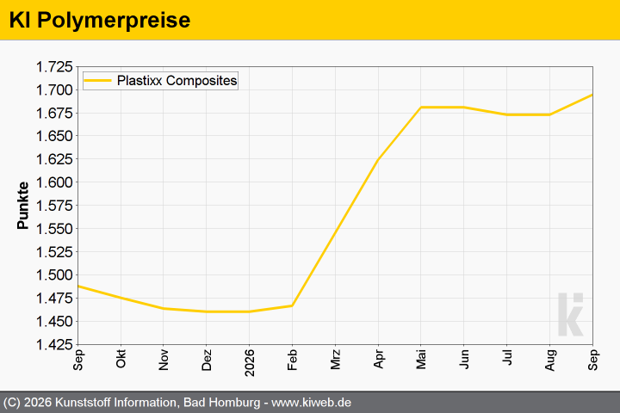
First resin price hikes as early as September / Price increases continue amid rising styrene costs in October / Demand could pick up in the coming weeks / Glass fibers also firmer
In September, initial transactions for ortho resins were mostly at rollover prices. From mid-month onward, however, contract prices rose noticeably, reaching premiums of up to +100 EUR/t. Imported goods, in particular, were offered only at significantly higher prices. European producers seized the opportunity and followed suit. Demand, on the other hand, remained virtually unchanged from the previous month. Order intake from the E&E sector remained satisfactory, and specialty applications for the construction industry also showed a slight improvement. The automotive industry, on the other hand, continued to underperform as usual. This could change in October: processors’ order books are already quite well-filled. Stable demand is expected to continue into November—according to the KI panel, the volume of demand could even exceed that of the same period last year.
This will have a noticeable impact on prices. Even the significant premium of +279
EUR/t on the styrene contract is likely to drive up resin prices. Added to this is the
rise in import costs due to increasing transportation expenses. The situation is similar for glass fibers
: Starting in the fourth quarter, producers hope to finally achieve margin improvements
.
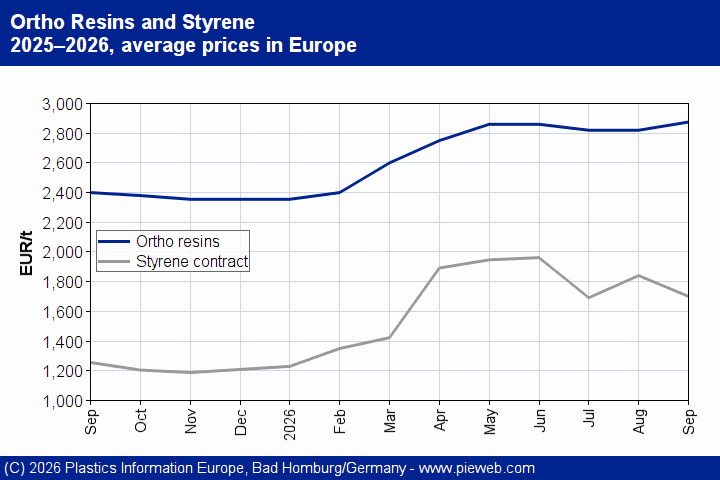
Composites/GRP September: Resin prices have already begun to rise in September / Asking prices continue to rise in October as the cost of styrene increases / Demand could pick up in the coming weeks / Glass fiber prices are also firmer
In September, the first ortho resin transactions were mostly concluded at rollover prices. Starting in the middle of the month, however, contract prices rose noticeably, with increases of up to EUR 100/t. Imported goods, in particular, were available only at considerably higher prices. European producers took advantage of the situation and followed suit.
Demand, by contrast, remained virtually unchanged from the previous month. Orders from the E&E sector remained satisfactory, and specialty applications for the construction industry also showed a slight improvement. The automotive industry, however, had still not returned to its full potential. This could change in October, as converters’ order books are already quite full. Demand is expected to remain stable through November, and the PIE panelists believe it could even exceed the level recorded for the same period last year.
This will likely have a noticeable impact on prices. The clear increase of 279 EUR per metric ton in the styrene contract alone is enough to drive up resin prices. In addition, imports are becoming more expensive due to higher transportation costs. The situation for glass fibers is similar: producers are finally hoping to improve their margins as the fourth quarter begins.